To see which supplier payments fall due in the next four weeks against the cash you will have, put every approved bill into the cash forecast on the date it will actually be paid, beside expected receipts, payroll, tax and other committed payments. Then read the forecast balance on each payment date. The payment run is decided against the cash you will have on the day each payment leaves.
The accounts payable ageing report tells you what you owe. The bank balance tells you what you have today. Neither tells you whether you can pay a bill on the day it falls due, because that depends on everything that leaves and arrives in between. Accounts payable forecasting treats bills as dated outflows in the cash forecast, so a tight week shows while there is still time to agree a different date with a supplier.
Why A Payment Run Set From Today's Balance Goes Wrong
A payment run set from today's bank balance and the ageing report checks the bills against cash that will not all be there when they leave. Payroll, PAYE, VAT and rent come out of the same accounts in the same weeks, and customer receipts arrive on their own timetable. The shortfall sits between today and the payment date, where neither report looks.
So the team either pays everything due and finds the account tight when payroll and a large supplier run go out in the same week, or it holds payments by feel. That strains supplier relationships and tells nobody whether the hold was needed.
Due Date And Payment Date Are Different Numbers
A bill's due date is what you agreed with the supplier. Its payment date is the day the money leaves your account, set by your payment-run day, any revised date you have agreed and how you pay. A payables forecast keeps both: the due date for the supplier relationship, and the payment date for the cash.
A bill due on a Wednesday is paid in Friday's run. A supplier agrees to take a large invoice in two parts. Neither is late payment. The Association of Corporate Treasurers describes the short-term operational forecast as built up from actual accounts payable and receivable data and expected disbursements, generally over a rolling 13 weeks. ICAEW's cash flow principles ask finance teams to assign expected, worst-case and best-case dates to payments as well as receipts.
No official figure measures how businesses of 11 to 50 staff pay their suppliers. The nearest come from large businesses. Large UK businesses reporting for 2025 took a median of 32 days to pay, and the median share of invoices paid after the agreed terms was 15% by number and 14% by value, in the Department for Business and Trade's self-reported statistics of July 2026. Our guide to how payment terms and late payment shape your cash timing covers the receiving side of the same gap.
What Goes Into A Four-Week Payables View
A four-week payables view needs approved bills on their payment dates, committed outgoings that are not yet bills, expected customer receipts on the dates customers usually pay, and the reconciled opening balance. Miss one and the view can no longer show the cash on the day each bill is paid.
Bills awaiting approval or in dispute stay out of the run until they are settled. The committed outgoings (net pay, PAYE and National Insurance, pensions, VAT, rent, loan repayments and direct debits) are often the largest movements in the window, and none of them appears on a payables report. Receipts go in on the dates each customer usually pays, so the view does not spend cash that has not arrived. The opening balance is the reconciled balance of the accounts the payments come from.
Four weeks is a working choice rather than a standard: long enough to see two or three supplier runs, a payroll and a tax date together. It sits inside the longer forecast. How long cash lasts if receipts stop is a different reading, set out in how many weeks of cash cover your business has.
How To Run The Payment Run Against The Forecast
Refresh the forecast from the ledger, list the payments due in the next four weeks by payment date, and read the forecast balance on each date against the team's floor. Then decide whether each bill is paid, held or moved by agreement, record the decision in the forecast, and report it to the finance director before the run is released.
CPA Australia's small-business guide (2010) describes a payment run held on a set day, with no change to an approved payment date without authorisation. The forecast adds the input those controls leave out: the balance on the day each payment leaves.
Step 1: Refresh the forecast from the ledger. Reconcile the bank accounts, bring in new bills and receipts, and clear estimates that actuals have settled.
Step 2: List the payments due in the next four weeks by payment date. Group bills by run, with payroll, tax and other committed payments in the same list.
Step 3: Read the forecast balance on each payment date. If it stays above the team's floor on every date, the run goes as planned.
Step 4: Decide pay, hold or agree a new date. Where a date dips below the floor, look first at receipts to chase and spending not yet committed. If a supplier bill must move, talk to the supplier before it falls due, agree the new date or staged payments, and confirm it in writing. A date the supplier has not agreed is a late payment.
Step 5: Record each decision on the bill in the forecast. Move it to the agreed date, or split it into the agreed parts, and note why.
Step 6: Report the run to the finance director. One line per decision: the bill, the date it now leaves, the balance it protects.
Our guide to keeping a cash flow forecast up to date as plans change covers the receivables side: keeping customer dates and plans current between runs.
A Worked Example: Four Weeks Of Bills, Payroll And Tax
On the ageing report and the bank balance, this invented business has £75,000 to spare across four supplier runs. On the forecast, the balance falls £23,000 below the team's floor on one Friday, and two changes agreed with suppliers 18 days ahead fix it.
Everything here is invented except the UK statutory dates. Larkfield Partners Ltd is a fictional company with 38 staff and a finance team of four, on Xero. On Monday 9 November 2026 the reconciled balance is £236,000, the floor is £75,000, and the ageing report shows £161,000 of approved bills for the next four Friday runs. The forecast adds VAT collected by Direct Debit on 11 November, three working days after the Saturday 7 November deadline; PAYE and pensions ahead of Sunday 22 November; net pay on the 25th; rent; and expected receipts.
| Dates | Movements | Balance as forecast | After the two agreements |
|---|---|---|---|
| Mon 9 Nov | Opening reconciled balance | £236,000 | £236,000 |
| 10–13 Nov | Receipts £48,000; VAT £64,000; supplier run £41,000 | £179,000 | £179,000 |
| 17–20 Nov | Receipts £61,000; PAYE, NI and pensions £38,000; supplier run £29,000 | £173,000 | £173,000 |
| 24–25 Nov | Receipts £18,000; net pay £102,000 | £89,000 | £89,000 |
| 26–27 Nov | Receipts £21,000; supplier run £58,000 (after the agreements, £19,000) | £52,000 | £91,000 |
| 30 Nov–1 Dec | Receipts £44,000; rent £18,000 | £78,000 | £117,000 |
| 3–4 Dec | Receipts £37,000; supplier run £33,000 (after the agreements, £50,000) | £82,000 | £104,000 |
The low point is Friday 27 November, £23,000 below the floor, in the week net pay leaves and the largest supplier run goes out. In the first week the finance manager agrees two changes, each in writing with the supplier concerned:
A £22,000 bill due on 27 November will be paid on Friday 11 December. The forecast's payment date moves to match.
A £34,000 bill due on 27 November will be paid in two staged payments of £17,000, on 27 November and 4 December. The bill is split in the forecast to match.
The low point becomes £89,000 on 25 November, above the floor on every date. Nothing was paid late: both suppliers agreed before the bills fell due, and the £22,000 sits in the forecast on 11 December for the next review to see.
Which Payments Come First
No professional body or tax authority publishes an order of payment for a business that is trading normally. In practice the dates for payroll and tax are fixed and the dates for supplier bills are agreed, so the run protects the fixed dates and, where cash is tight, agrees new supplier dates in advance rather than missing them.
Statutory dates carry their own costs. HMRC charges interest on late VAT from the first day it is overdue and a first penalty from 16 days, and late PAYE can bring interest and penalties too.
Supplier dates change only by agreement. CPA Australia's guide tells finance teams to talk to suppliers when a payment needs to move and to put what is agreed in writing, and the UK Small Business Commissioner advises talking to the supplier as soon as possible. The Commissioner describes late and long payment times as disrupting small businesses' cash flow. Its Fair Payment Code, running since December 2024, gives gold to businesses that pay at least 95% of all invoices within 30 days.
GOV.UK's guidance is that an agreed payment date should usually fall within 60 days between businesses and 30 days for public authorities, and that a longer term must be fair to both sides. The Commercial Payments Bill, before Parliament in October 2026, would make those limits caps for most contracts, with exemptions. It is not yet law.
How Float Does This Today
Float connects to Xero and QuickBooks Online today, with Sage Intacct coming soon (you can join the Sage Intacct waitlist), and imports from your ledger once a day at an hour you choose, with a manual sync before a run (Step 1). The connection is one-way: Float never writes back to your accounting system. The forecast starts from the reconciled ledger balance of the bank accounts you include, not a bank feed.
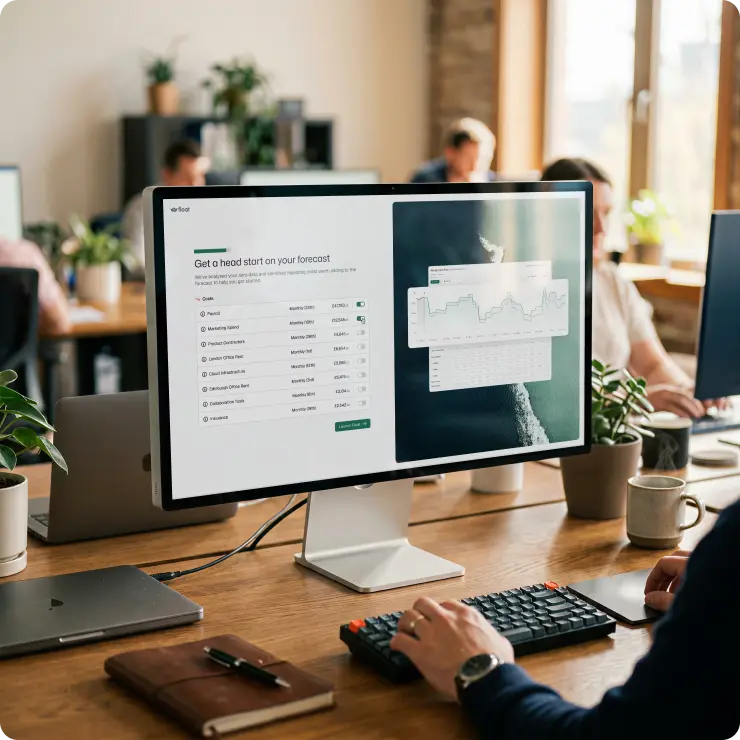
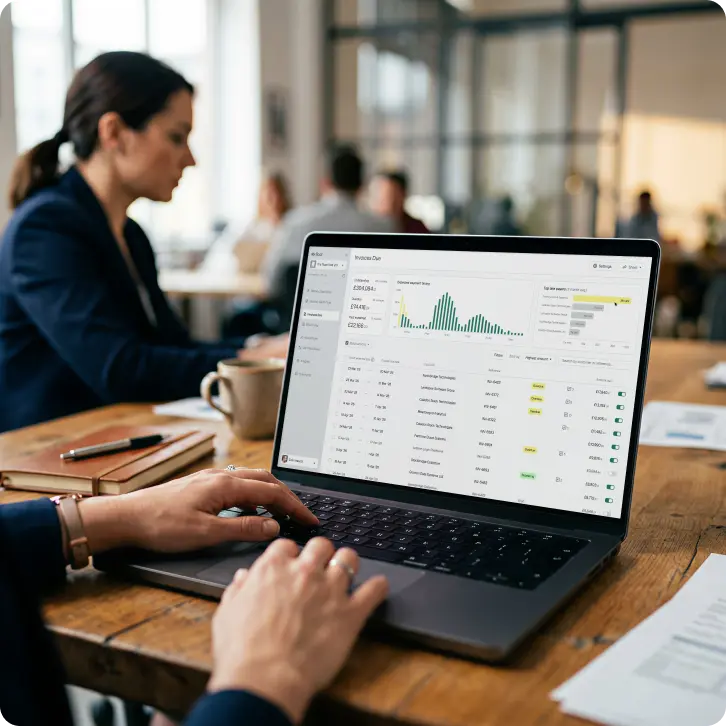
Bills appear on their expected dates in the weekly view, and day by day in the list view, beside invoices and budgets (Step 2). Payroll, rent and other outgoings not yet billed go in as budgets on their dates, and actuals replace them as they land. Automatic VAT and GST forecasting is available for Xero users only. Set a threshold and Float shows on screen the date the balance is due to cross it (Step 3). It is a date to read, not an alert.
Expected dates on bills can be moved singly or in a batch, and a bill can be split into several expected payments on different dates, with the forecast balance updating as you go (Step 5). Moving a date in Float changes the forecast; the supplier's terms and your ledger stay as they are. The move records an agreement already made, and a comment on the bill says why. For Xero users only, Smart Expected Dates applies each supplier's typical payment timing to new bills. For Step 6, the team exports a PDF or CSV when needed, and the finance director and CEO can follow the forecast as read-only viewers, one of four user roles.
Float's direction is to build a fuller record of how cash moves through a business, including when suppliers are paid and how forecasts compare with actuals, so finance teams can see the payments they need to make against the cash they have and expect to receive.
What Float Does Not Do
Float does not pay suppliers, approve bills or run the payment run, and it does not connect to your bank. Approval and payment stay where they are today; Float shows the cash on each payment date.
Frequently Asked Questions
How do we see which supplier payments are due in the next four weeks against the cash we will have?
Put every approved bill into the cash forecast on the date it will be paid, beside expected receipts, payroll, tax and rent, and read the forecast balance on each payment date against your team's floor. The ageing report and today's bank balance cannot show this, because neither includes what else moves before each payment.
What is accounts payable forecasting?
Accounts payable forecasting places each supplier bill in the cash forecast on the date the money will leave, rather than treating payables as a list ordered by due date. It keeps the due date for the supplier relationship and adds a payment date for the cash, so the payment run is decided against the balance on each date.
How can a finance team spot a cash shortfall six to eight weeks before it happens?
Keep a rolling forecast of at least 13 weeks with every dated payment and receipt in it, refreshed from the ledger each week. A shortfall shows as the first date the balance crosses your floor. Payroll, tax and large supplier runs falling close together are a common cause, visible as soon as their dates are in.
How should a finance team of three to eight run a weekly cash meeting, and what tool supports it?
Use a short fixed agenda: reconciled cash, receipts that moved, payments due, the forecast low point and anything to escalate. Our guide to running a weekly cash review in a finance team of three sets out the items and owners. A forecasting tool connected to your accounting ledger, such as Float, holds the numbers the meeting reads.
How often should a business do a payment run?
No rule fixes it. CPA Australia's small-business guide describes a structured monthly run on a set day. Whatever the frequency, choose one the forecast can show two or three runs ahead, so a tight date is visible while there is still time to agree a change with a supplier.
Can we agree a later payment date with a supplier?
Yes, if the supplier agrees. Talk to the supplier (or vendor) before the bill falls due, agree the new date or staged payments, confirm it in writing, then move the payment date in your forecast to match. A later date the supplier has not agreed is a late payment.
Float is built for in-house finance teams of three or more that decide a payment run every week. It puts every bill on its expected payment date beside payroll, tax and customer receipts, synced daily from your ledger. Start a free 14-day trial and read next month's supplier runs against the cash you will have.