FP&A software plans and explains performance: budgets, profit forecasts, variance against plan and board reporting, mostly by month and a year or more ahead. Cash flow forecasting software shows the cash the business will hold in each of the coming weeks, built from dated receipts and payments. A finance team that answers cash questions every week needs the weekly cash view whether or not it runs a planning tool, and a team that also builds multi-year driver models with many budget holders needs both.
The word "forecast" covers two jobs. A planning forecast asks whether the business is on course for the year. A cash forecast asks whether the balance holds in the week the VAT bill and the bonus run both leave. The two use different inputs at a different level of detail. Pick the tool by the decisions you make and how often you make them, not by the word "forecast".
Why The Question Comes Up At This Size
It comes up when a business has a budget and starts getting weekly cash questions the budget cannot answer. The budget is a monthly profit plan, approved by the board. The CEO's question is about a specific week.
At £5m to £10m revenue, the annual budget usually sits in a large spreadsheet or a planning tool. Then the questions change. Can we pay the VAT bill and the bonus run in the same week? Which week gets tight if our largest customer pays a month late? The budget shows April as profitable. It does not show which day in April the cash leaves.
No professional body sets a revenue or headcount at which a business needs FP&A software or an FP&A team. The Association for Financial Professionals (AFP) notes that a small company may have no defined FP&A role, only a finance employee whose responsibilities include FP&A. At this size one team usually does both jobs.
What FP&A Software Is For
FP&A software supports the plan and the explanation of results against it: budgeting, profit forecasting, driver-based planning on the profit and loss, variance against plan, and management and board reporting. It works mostly in months, across the budget year and beyond, and the finance director or CFO runs it.
The AFP, the only professional body that publishes a definition, describes FP&A as the function within the office of the CFO that supports strategic decisions through integrated planning, budgeting and forecasting, performance management and financial analysis. In practice that means the budget, agreed with budget holders; the re-forecast, monthly or quarterly as results come in; driver models for headcount, pricing and margins; and the board pack. ACCA's guidance on rolling budgets describes adding a period as each one expires, so the budget always extends one year into the future.
A fuller planning model links the profit and loss, balance sheet and cash flow so they reconcile. ICAEW calls this an integrated forecast; others call it three-statement or three-way forecasting. So FP&A does forecast cash. The AFP counts cash flow visibility among FP&A's processes. That cash figure comes out of the plan, usually by month, after profit and the balance sheet have been modelled.
What Cash Flow Forecasting Software Is For
Cash flow forecasting software shows the cash the business will hold in each coming week, starting from today's balance and the receipts and payments already known. It holds the expected date of each invoice and bill, moves those dates when customers slip, and shows the week the balance gets tight. The finance manager or controller runs it weekly.
The jobs are operational. Each invoice and bill sits in the week the team expects it to be paid, and when a customer says payment will be three weeks late, the forecast moves with it. The view rolls: the Association of Corporate Treasurers' knowledge hub describes operational cash forecasts as generally covering the next 13 weeks on a rolling basis, and thirteen is a convention rather than a rule. The forecast shows which week the balance crosses the floor the team has set. A late customer or an early hire is tested against it before the decision is made. And the CEO sees the same numbers every week.
The AFP draws the same line. Treasury and FP&A both produce forecasts, it says, but both their objectives and general approaches to the task are different. With no treasurer, the finance team does both. Our guide to the operational cash layer sets out where the weekly job sits.
Why A Profit Forecast And A Cash Forecast Disagree
They disagree because profit is recorded when income is earned and costs are incurred, while cash moves when invoices are paid. A month can be profitable on the plan and still be short of cash in one week of it. ACCA puts it plainly: a healthy profit does not necessarily mean a healthy cash flow.
The usual causes are timing. Customers pay after the sale is recorded. Tax falls on fixed dates: in the UK, VAT is due one calendar month and seven days after the end of the VAT period, whatever the month's trading. Costs accrued across the year, such as bonuses and annual insurance, are paid in one week. Equipment is charged to profit over its life but paid for up front, and loan principal leaves the bank without touching the profit and loss. Stock is bought before the sale is recorded.
Take an invented example. A business with £8m revenue plans an April profit of £70,000. The weekly cash view tells a different story. The week beginning 6 April opens at £310,000. Receipts of £95,000 come in. The VAT payment for the quarter to 28 February, £165,000, is due on 7 April. The annual bonus run of £120,000, accrued across the last year's plan, is scheduled for 10 April. Supplier payments take £60,000. The week closes at £60,000, against a floor of £100,000 the team has set. The largest customer's £140,000 invoice, due on 31 March, is now expected on 20 April. The month still ends profitable. The finance director moves the bonus run to 24 April, after the expected receipt, and the balance holds.
The professional bodies describe the short-term cash forecast as built from dated receipts and payments, often called the direct method. The other route derives cash from a projected profit and loss account and balance sheet, the indirect method. The AFP notes, in an article on the cash flow statement, that the direct method is often used for short-term planning of under three months. Our guide to the P&L budget and the cash flow forecast builds each one month by month.
The Comparison, Job By Job
Each tool is built for a different set of jobs, and some jobs can be done in more than one. Products vary, so test any tool against the rows that matter to you.
| Job | Accounting software | Cash flow forecasting software | FP&A software |
|---|---|---|---|
| Set the annual budget | Some hold a simple budget against the ledger | Holds budgets as cash expectations; not the plan of record | Its main job |
| Forecast profit by month | Not its job | Not its job | Its main job |
| Model headcount and pricing drivers | Not its job | Models the cash effect of a hire or a price change | Its main job |
| Explain variance against plan | Reports actuals against a budget, where it holds one | Compares cash actuals with cash budgets | Its main job |
| See dated cash for the next 13 weeks | Built-in planners cover the near term for one company (see our comparison) | Its main job | Possible if the model holds dated receipts and payments by week |
| Move an invoice's expected date when a customer slips | Holds the due date | Its main job | Possible if the model holds invoice-level detail |
| Spot the week the balance crosses a threshold | Not its job | Its main job | Possible in a weekly cash model |
| Produce the weekly cash report for the CEO | Not its job | Its main job | Possible in a weekly cash model |
The "possible" cells matter. Any planning model can produce a weekly cash view if it holds dated receipts and payments and someone updates them every week. The question is whether your team does that work, and where.
Do You Need Both? Five Questions
You need both when your team makes weekly cash decisions and also maintains a plan that a cash tool cannot hold. Answer these five questions for the business you run now, not the one you expect in two years.
How often do decisions turn on cash? If the CEO asks about cash every week, or payments are held or released week to week, you need a weekly cash view.
Do payment dates move enough to change the month? If a few large invoices paid late can swing the balance by more than your cash floor, you need expected dates at invoice level.
Does the board need a multi-year driver model, or a profit and loss account and balance sheet forecast that reconcile? If so, that is planning software's job, or a well-built spreadsheet's.
How many people contribute to the budget? If department heads each own a budget and submit it through a review cycle, a planning tool earns its place.
Who keeps the weekly cash detail current, and where? If your planning model already holds dated receipts and payments and someone updates them weekly, you may not need a second tool. If that detail lives in a separate spreadsheet one person rebuilds, it is already a second tool, without the controls.
Mostly cash answers (1, 2 and 5): a cash flow forecasting tool alongside the budget you already have. Mostly planning answers (3 and 4): a planning tool, checked against the weekly cash rows in the table. Both: both, with the budget feeding the cash forecast.
How The Two Work Together
The plan sets the budget, and the cash forecast runs weekly against it and shows the timing. Budget figures go into the cash forecast as expected income and costs, and the forecast moves each one to the week the cash will actually move. The AFP's advice is to align the short-term cash forecast with the long-term corporate model.
That takes three habits. The cash forecast starts from the budgets the board approved. When the plan is re-forecast, the cash forecast's budgets are updated to match. When the two disagree about a month, someone finds out whether it is timing or a change in the plan. Our guide to moving from the annual budget to a rolling cash forecast covers who owns each step.
No professional body says the two must sit in one system, and none defines FP&A software and cash flow forecasting software as categories or says which to buy first.
How Float Does This Today
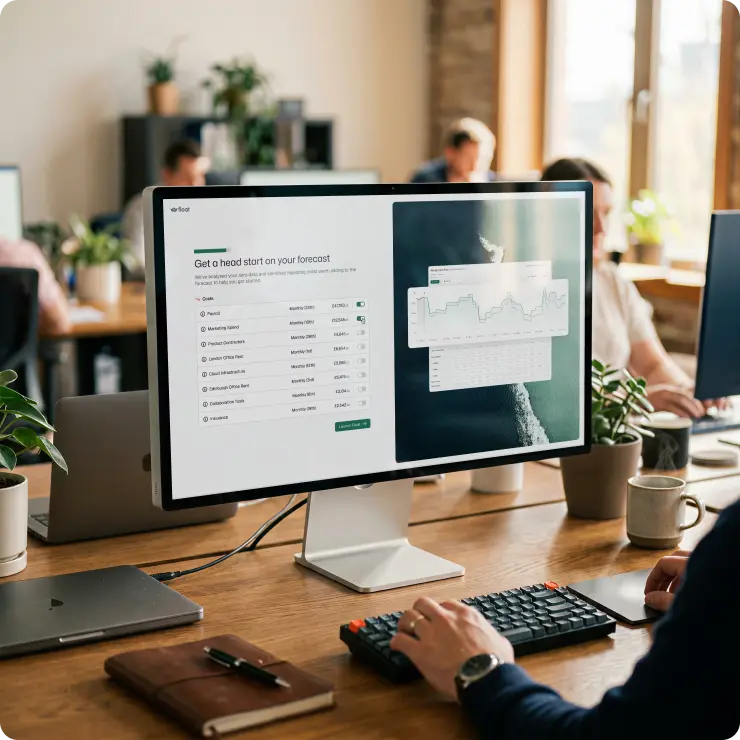
Float is cash flow forecasting software for in-house finance teams. It does the cash jobs in the table and works alongside whatever holds your plan. Float connects to Xero and QuickBooks Online today, with Sage Intacct coming soon; you can join the Sage Intacct waitlist.
Cash only, by design. Float builds its forecast from invoices, bills, bank transactions and budgets. It does not produce a profit and loss forecast, a balance sheet forecast or a three-way forecast. The reasoning is in our piece on why Float forecasts cash and not the P&L.
Dated cash for the next 13 weeks. Float builds a weekly cash forecast for the next 13 weeks on ledger data from your accounting system, starting from the reconciled ledger balance of the bank accounts you include. The sync runs one way, once a day at an hour you choose, with a manual sync on demand. Float never writes back to your accounting system.
Budgets from your plan. You enter budgets or paste them in from a spreadsheet, and Float suggests regular income and costs from your history. As invoices, bills and transactions land, the actual figures replace the budgets. Float has no connection to any planning tool, so the budget is copied in, not linked.
Expected dates. You can move the expected payment date on any invoice or bill. On Xero-connected companies, Float can apply each customer's and supplier's average days paid late, from your own payment history; on other connections, expected dates are moved by hand.
What-if questions. Scenario layers sit on top of the base forecast and change budgets only.
Variance, the tight week and the report. Budget variance covers last month or the last three months, with the accounts most over or under budget. Float shows the date the balance is due to cross a threshold you set. You export the forecast as a PDF or CSV when you need it, and four user roles include a read-only viewer for the CEO.
Where This Is Going
Across finance software, planning tools are becoming more granular and more connected, and accounting systems are starting to interpret what they record rather than only hold it. Float's view is that the weekly cash job should move the same way: from a forecast the team rebuilds at intervals to a cash system the team runs, one that keeps reconciling what was expected with what happened, reassesses what is likely to happen next and shows where attention is needed. That rests on a richer record of how cash moves through the business, when customers pay, when suppliers are paid and how forecasts differ from actuals, connected to bank balances and to the context that today sits outside the ledger. One condition holds throughout. The numbers stay traceable and explainable, and the finance team stays in control of them.
When An FP&A Tool Is The Right Call
An FP&A tool is the right call when the work is planning the business rather than running its cash: multi-year plans, driver models, integrated three-statement forecasting, departmental budgets with many contributors, and a board pack that consolidates the profit and loss account and balance sheet. A cash flow forecasting tool does not do these jobs, and Float does not either.
If your planning model already produces a dated weekly cash view that someone keeps current, a separate cash tool may add little. If your question is how to control payments, funding and currency risk at scale, that is a treasury management system's territory, and our guide to treasury systems and forecasting tools covers it.
Frequently Asked Questions
What is the difference between cash flow forecasting software and FP&A software for a finance team, and do we need both?
FP&A software plans and explains performance: budgets, profit forecasts, driver models and variance against plan, mostly by month. Cash flow forecasting software shows dated cash for the coming weeks, from expected receipts and payments. A team that makes weekly cash decisions needs the cash view; a team that also runs multi-year driver models with many budget holders needs both.
We use Xero for accounting and a planning tool for budgets, what should we use for week-to-week cash?
Use a cash flow forecasting tool that reads your Xero ledger and holds a rolling weekly forecast with expected payment dates on invoices and bills. Your planning tool holds the budget and Xero holds the record. Copy the budget into the cash forecast as expected income and costs, then move each figure to the week the cash will actually move.
How does Float cash flow forecasting fit alongside Xero and an FP&A tool?
A cash flow forecasting tool sits between the two. Xero supplies the ledger: invoices, bills and reconciled balances. The FP&A tool holds the plan. The cash tool turns both into a weekly view of dated cash, with budgets copied in from the plan. Float does this for in-house finance teams, reading the ledger once a day.
What is FP&A software?
FP&A software is planning software used by the finance function to build budgets, forecast profit, model business drivers, compare results with plan and prepare management and board reports. It works mostly by month across the budget year and beyond. Many planning models can link the profit and loss, balance sheet and cash flow into one integrated forecast.
Does a small business need FP&A software?
Often not at first. No professional body sets a revenue or headcount at which a business needs FP&A software, and in smaller companies the planning work usually sits with a finance employee in a wider role. Planning software earns its place when many people contribute to the budget or the board needs multi-year driver models.
What is the difference between a cash flow forecast and a budget?
A budget is the plan for the year: income and costs by month, usually on the profit and loss basis, approved by the board. A cash flow forecast shows when cash will actually arrive and leave, starting from today's balance. A month can meet its budget and still be short of cash in one week of it.
Float is built for in-house finance teams of three or more that answer cash questions every week. If you are weighing a planning tool, a cash tool or both, the next step is a conversation with the Float team. Tell us what your budget looks like and what the CEO asks about cash each week, and we will show you where the weekly cash job sits. Book a conversation with the Float team.